
Regional banking company FB Financial (NYSE:FBK) missed Wall Street’s revenue expectations in Q3 2026, with sales flat year on year at $174.5 million. Its non-GAAP profit of $1.21 per share was in line with analysts’ consensus estimates.
Is now the time to buy FB Financial? Find out by accessing our full research report, it’s free.
FB Financial (FBK) Q3 2026 Highlights:
- Net Interest Income: $149.9 million vs analyst estimates of $153.5 million (1.8% year-on-year growth, 2.3% miss)
- Net Interest Margin: 3.8% vs analyst estimates of 3.9% (7.4 basis point miss)
- Revenue: $174.5 million vs analyst estimates of $180.8 million (flat year on year, 3.5% miss)
- Efficiency Ratio: 55% vs analyst estimates of 52.9% (211.7 basis point miss)
- Adjusted EPS: $1.21 vs analyst estimates of $1.21 (in line)
- Tangible Book Value per Share: $31.50 vs analyst estimates of $32.02 (5.6% year-on-year growth, 1.6% miss)
- Market Capitalization: $2.65 billion
President and Chief Executive Officer, Christopher T. Holmes stated, “Our results reflect continued organic growth momentum and solid profitability metrics. Annualized loan growth (HFI) was 9.68% for the quarter, annualized client deposit growth was 11.0%, and annualized total deposit growth was 8.82% when we net out the decline in brokered deposits. We are encouraged by the quality of opportunities in front of us and the pipelines we see across the Company. In addition, our recent $125.0 million subordinated debt issuance provides added flexibility to support future growth. We remain focused on providing value to clients and creating long-term value for our shareholders.”
Company Overview
Founded in 1906 and operating through more than a century of economic cycles, FB Financial (NYSE:FBK) operates FirstBank, providing commercial and consumer banking services across Tennessee, Kentucky, Alabama, and North Georgia.
Sales Growth
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management, and trading activities. Regrettably, FB Financial’s revenue grew at a sluggish 3.3% compounded annual growth rate over the last five years. This was below our standard for the banking sector and is a tough starting point for our analysis.
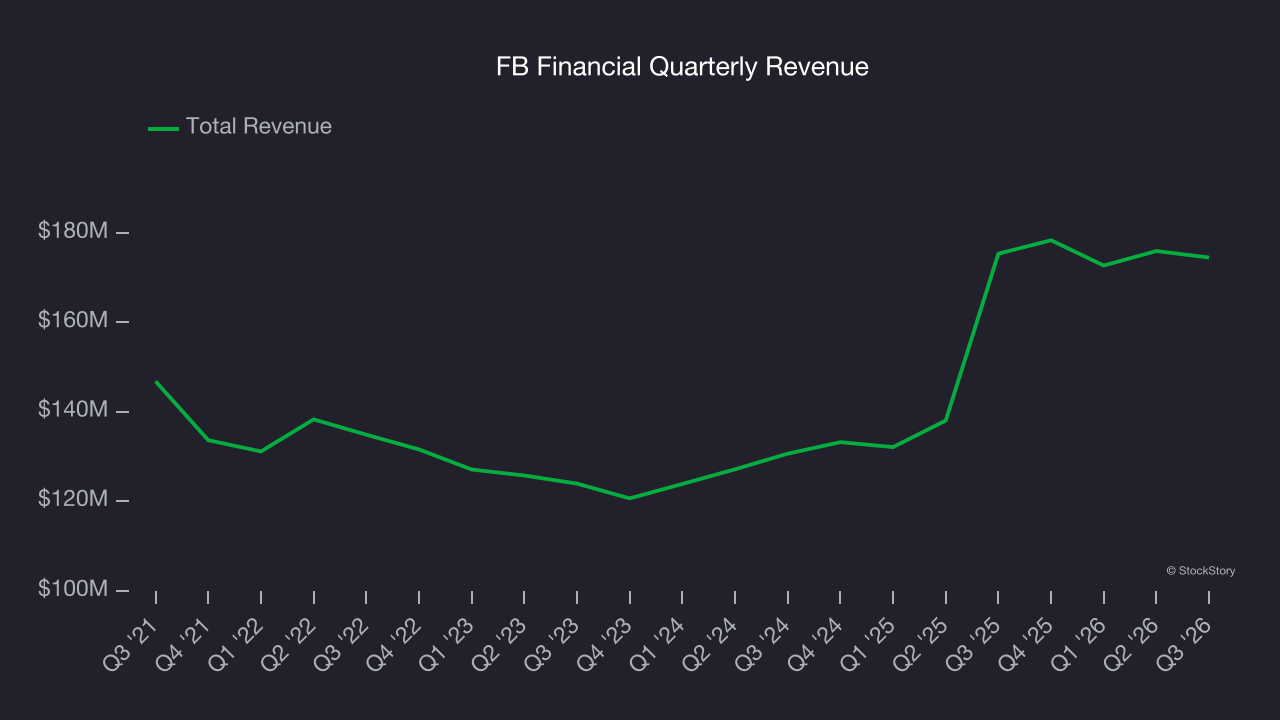
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. FB Financial’s annualized revenue growth of 18.2% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 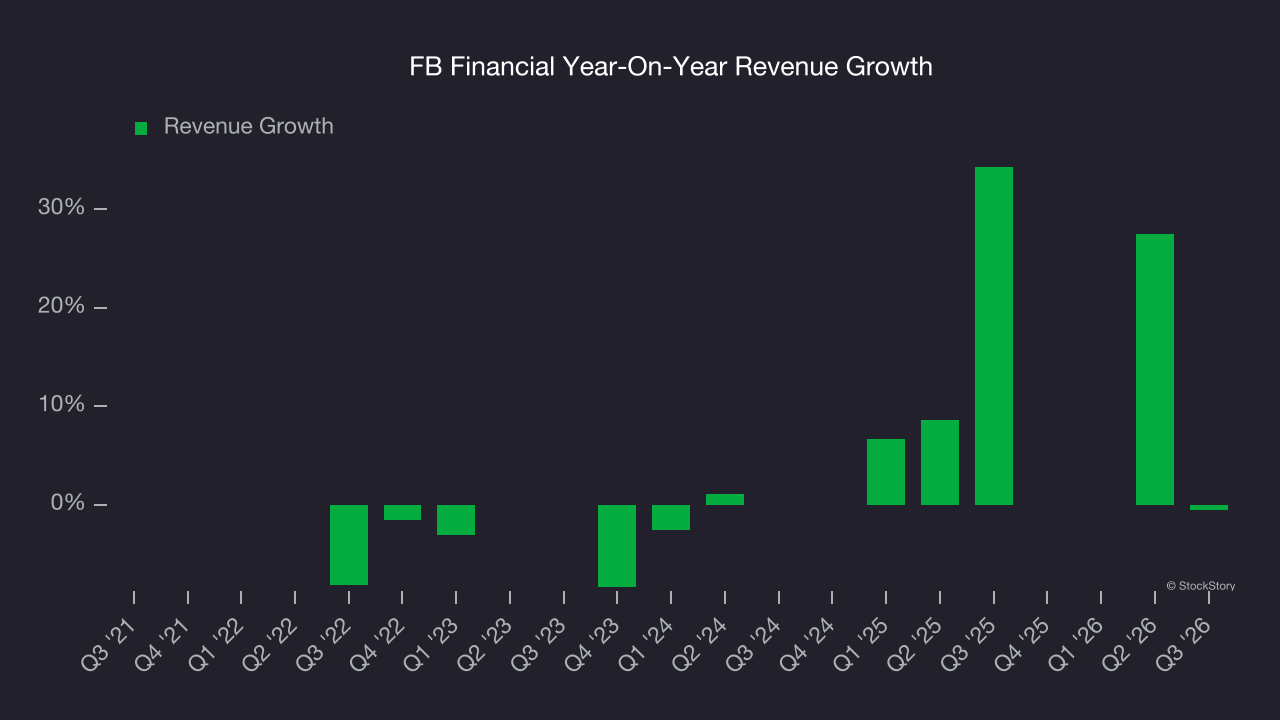 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, FB Financial’s $174.5 million of revenue was flat year on year, falling short of Wall Street’s estimates.
Net interest income made up 83.3% of the company’s total revenue during the last five years, meaning FB Financial barely relies on non-interest income to drive its overall growth.
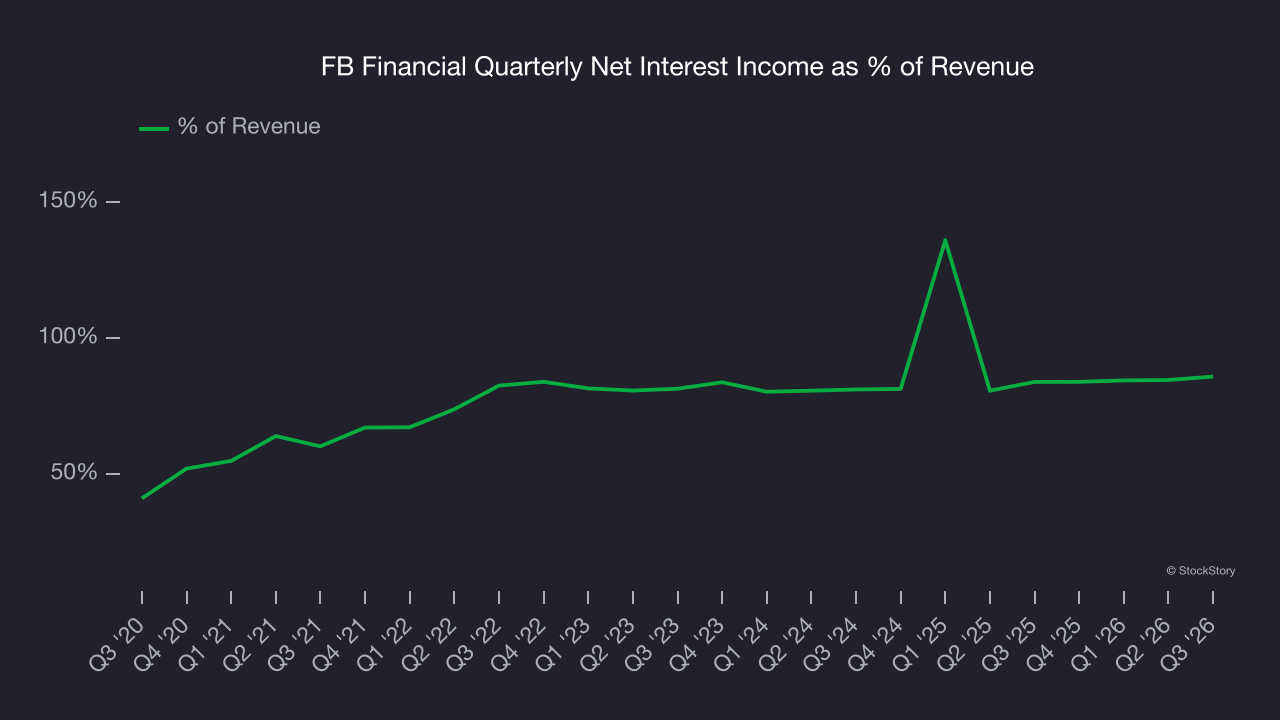
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone - its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Tangible Book Value Per Share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
This is why we consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation. EPS can become murky due to acquisition impacts or accounting flexibility around loan provisions, and TBVPS resists financial engineering manipulation.
FB Financial’s TBVPS grew at a decent 5.7% annual clip over the last five years. The last two years show a similar trajectory as TBVPS grew by 5.8% annually from $28.15 to $31.50 per share.
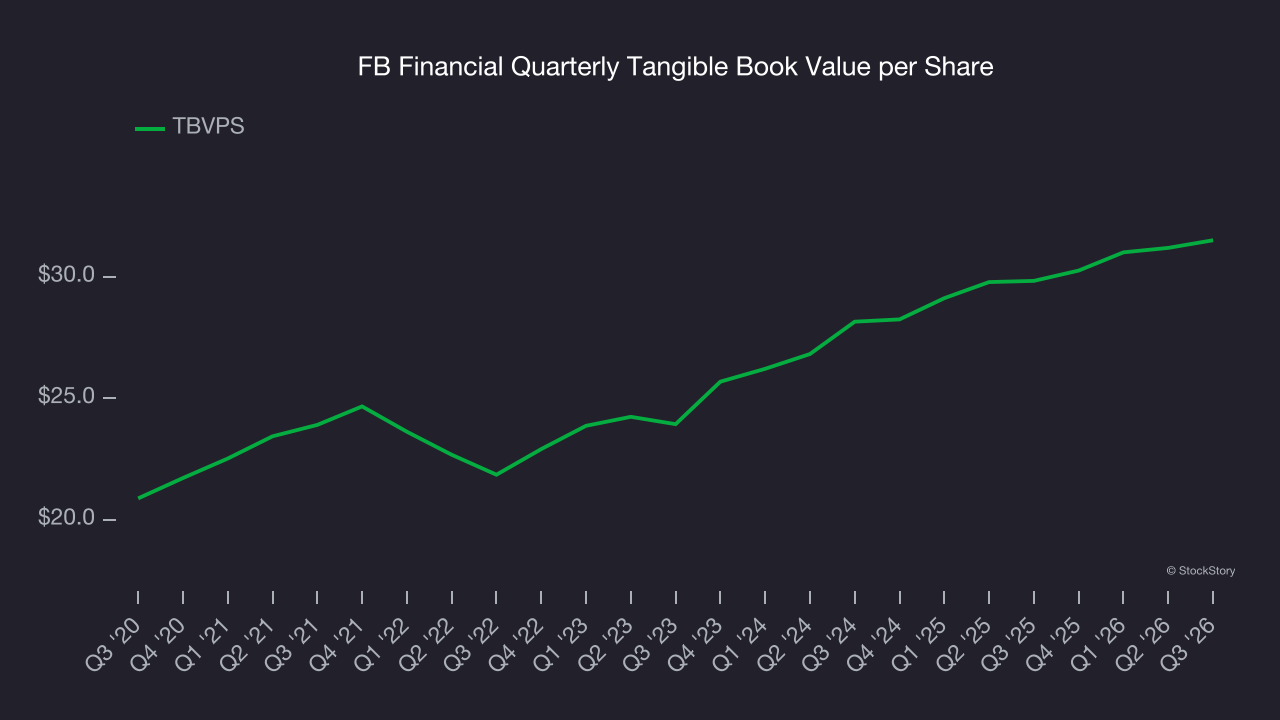
Over the next 12 months, Consensus estimates call for FB Financial’s TBVPS to grow by 13.7% to $35.81, decent growth rate.
Key Takeaways from FB Financial’s Q3 Results
We struggled to find many positives in these results. Its revenue missed and its net interest income fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock traded up 1.8% to $53.86 immediately after reporting.
So should you invest in FB Financial right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).